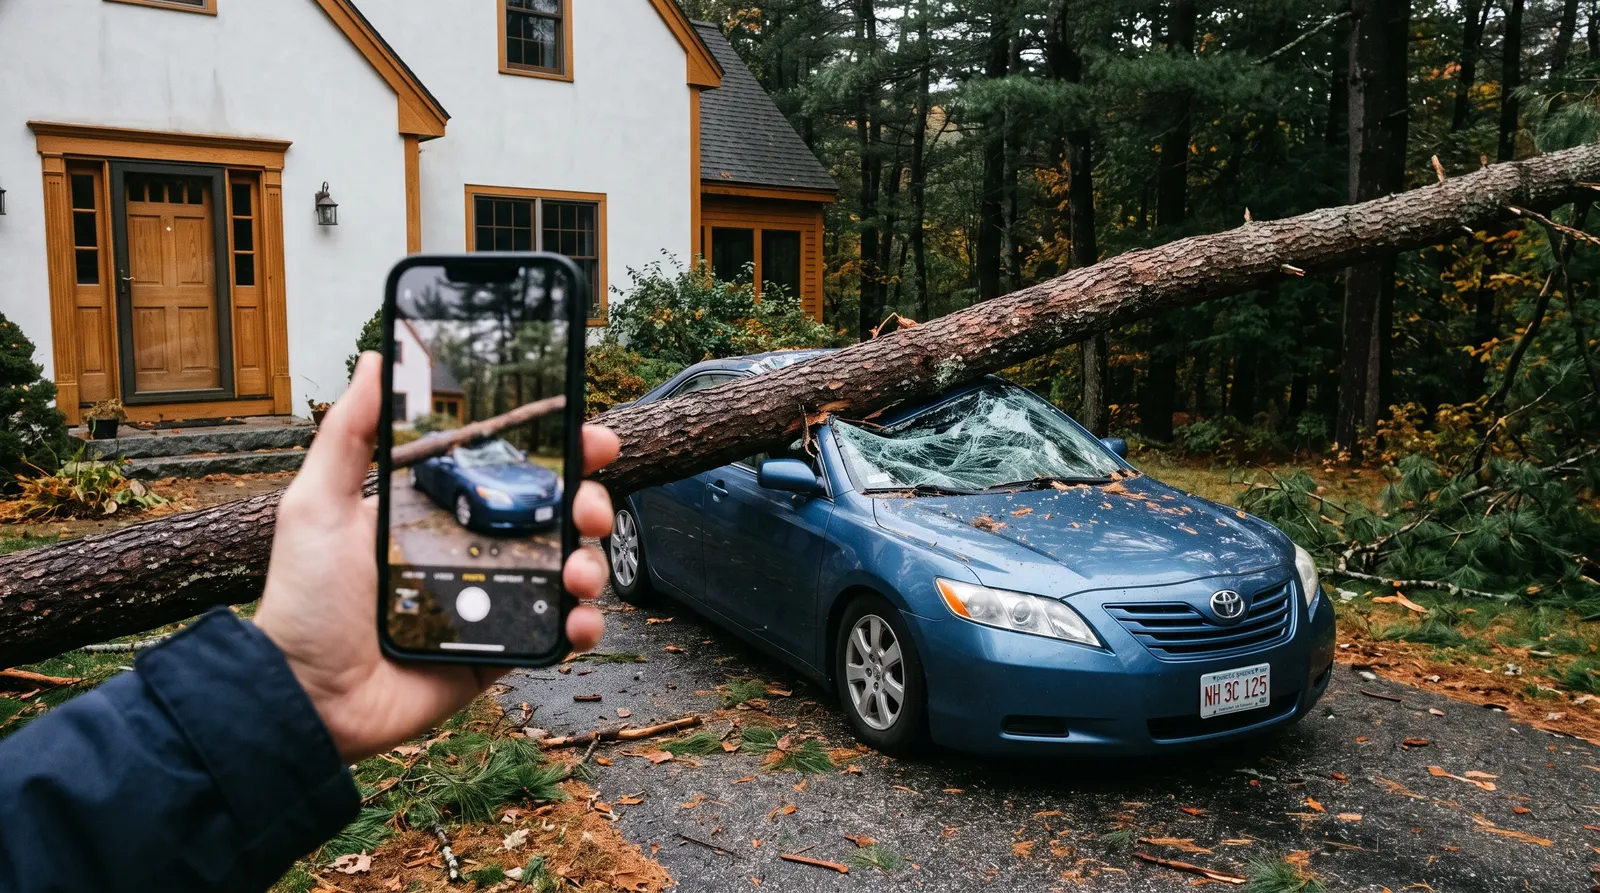
A tree fell on car situation is a comprehensive auto claim in almost every case, not a homeowners one, and that holds regardless of whose property the tree stood on.
A tree fell on my car insurance question has one answer: comprehensive coverage, not collision coverage and not the house policy. The storm and tree guide covers the rest of the damage, a roof leak after the same storm is a separate claim, and Emergency Services 24H routes tree work to licensed crews nearby.
It does not matter much whose tree it was.
It does not matter much whose tree it was: a city tree fell or a neighbour’s did, and a parked car in an apartment complex parking lot ends the same way as one on the drive.
If a tree branch fell onto a car during storm conditions, your own comprehensive coverage policy is the fast route.
Never approach a vehicle with power lines down across it. Check the policy limits and the deductible before you call customer service, and remember that a full coverage policy is a sales phrase rather than a coverage type, and a hit and run parked claim is a different cover again.
Tree fell on car: which policy pays
Home insurance or auto insurance?
Auto, specifically the comprehensive portion. Vehicles are covered by auto policies rather than property policies, so comprehensive is the route even when the car was on your own driveway and the tree was your own.
The half people get wrong is what the neighbor’s policy can do for them.
The exception he names is deferred maintenance - a maintenance issue that was known about and left undone - and what makes it actionable is documented prior notice: a dated email, a certified letter, or an arborist’s report that was sent to the tree’s owner before it came down.
The practical consequence runs in both directions.
This is what a named broker says about how these policies generally work, recorded with attribution.